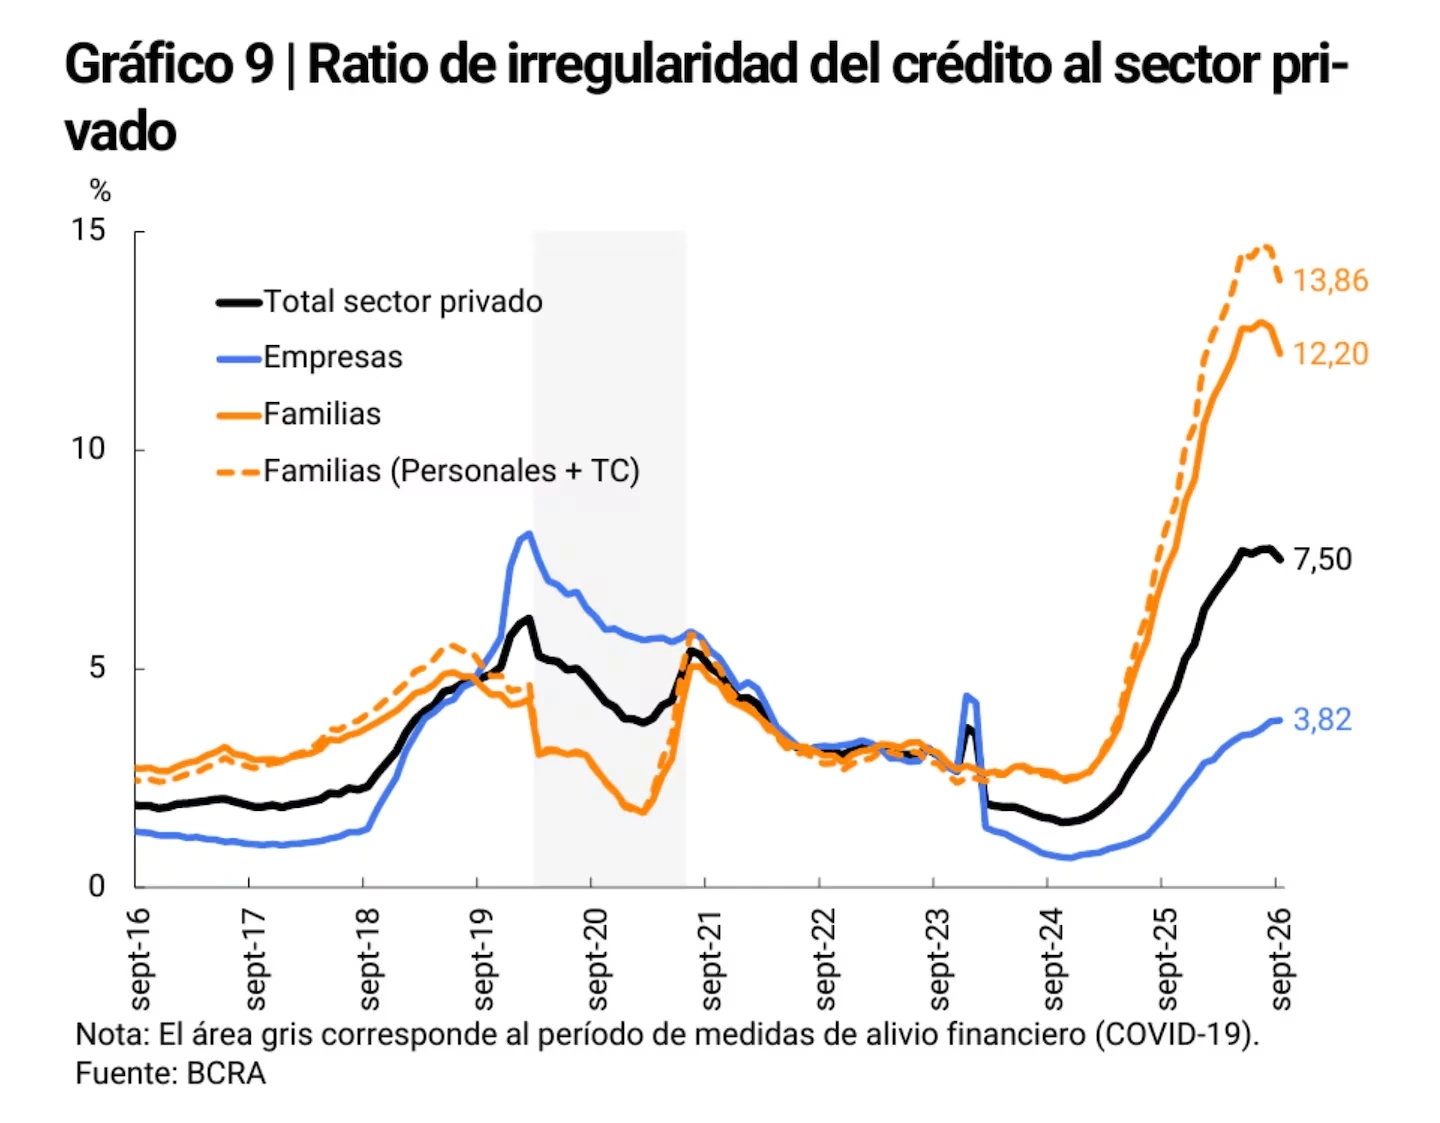
The delinquency of loans to families fell again in September and stood at 12.2% of the total financing granted, according to the latest Report on Banks published by the Central Bank of the Argentine Republic (BCRA).
The indicator recorded a improvement of 0.6 percentage points compared to August, when it had reached 12.8%. The evolution was also reflected in the overall financial system.
During September, overdue payments represented 7.5% of the total loan portfolio, down from 7.75% the previous month. Additionally, the balance of loans with delays recorded a reduction of 2.58% in real terms, according to data from the monetary authority.
The BCRA report.
Among the various financing lines aimed at households, credit cards stood out for showing the greatest monthly improvement. The irregularity of these loans fell by one percentage point to 11.2% of the total, compared to the 12.2% recorded in August.
Personal loans also showed a favorable evolution. In September, the delinquency of this line stood at 16.6%, representing a reduction of 0.5 percentage points compared to the previous month.
Meanwhile, the secured loans for families recorded a decrease of 0.4 percentage points and reached an irregularity of 7.8%. Mortgage lines also showed positive results: delays were at just 1.6% of the total, with a monthly improvement of 0.1 percentage points.
Another highlighted aspect of the report was the evolution of refinancings. In September, refinanced loans to households represented 3.9% of the total financing, while, within the loans with delays, the refinanced proportion reached 24.1%.
President Javier Milei.
In the business segment, the indicators also showed a considerably lower level of irregularity compared to that recorded among families. Overdue payments represented 3.8% of the financing granted to companies during September.
Within this universe, pre-financing and export financing lines recorded some of the lowest levels of irregularity, with only 0.6%. Document discounts reached 3.7%, current account advances were at 3.9%, and secured loans stood at 4.7%.
The data published by the Central Bank allows us to observe the evolution of the main credit indicators during September, with a reduction in family delinquency and improvements in various financing lines, especially in credit cards, personal loans, and secured loans.