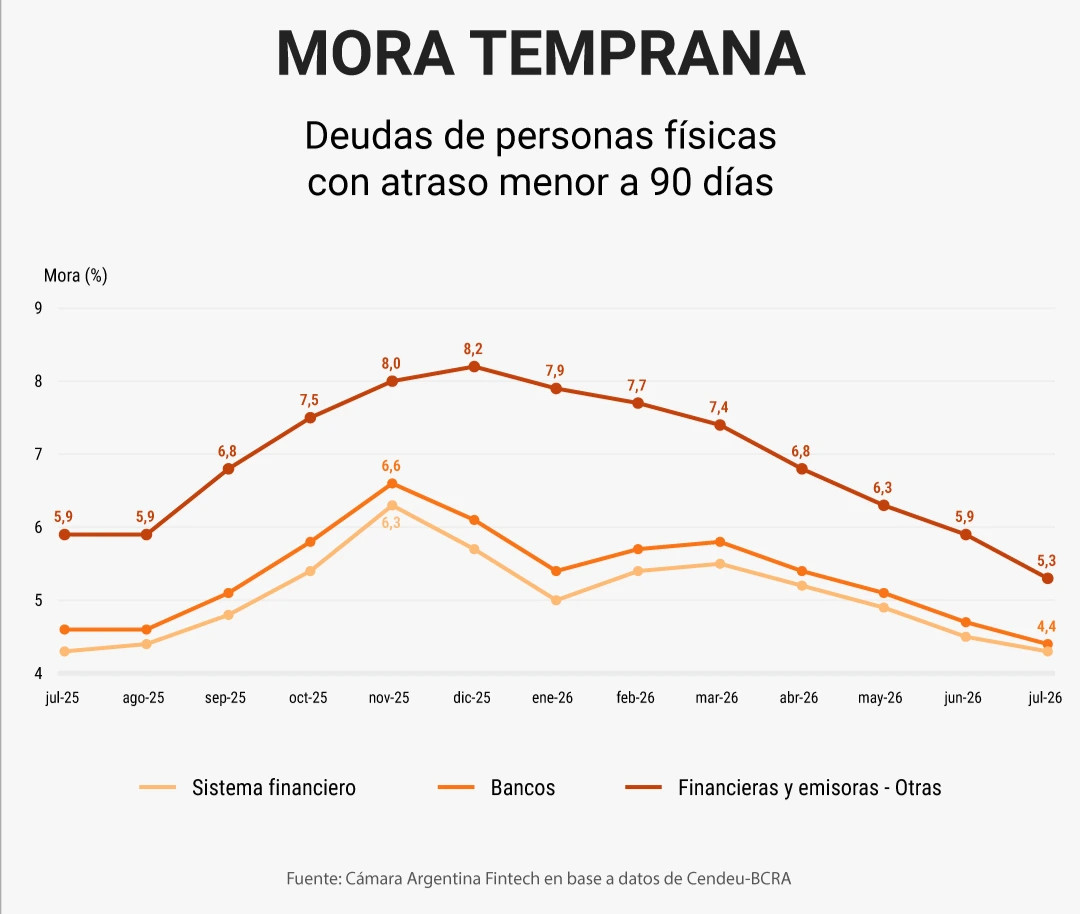
The amount of delinquent loans between 30 and 90 days has been decreasing since the beginning of 2026, with the indicator dropping from a maximum of 6.6% in November 2025 to 4.4% in July across the entire financial system.
The data comes from a report by the Argentine Fintech Chamber and reflects an improvement in loans classified in situation 2 by the Central Bank of the Argentine Republic (BCRA), meaning those that show delinquencies between 30 and 90 days.
The trend is also observed when analyzing the different segments of the system. In traditional banks, early delinquency dropped from 6.3% to 4.3% during the analyzed period. Meanwhile, financial institutions, card issuers, and wallets recorded a reduction from a maximum of 8.2% in December to 5.3% in July.
Early delinquency decreases
The behavior of this indicator provides a favorable signal regarding the evolution of the quality of credit portfolios. The reduction of early delinquencies shows that a smaller proportion of loans is entering the early stages of default.
A source from the sector used a comparison to describe this dynamic: “What the data shows is that the tap filling the ‘bucket of delinquency’ is contributing a smaller flow, which has been decreasing. But that doesn’t mean the water that was already accumulated disappears immediately.”
Another survey, conducted by the Austral University, also detected a sign of improvement when analyzing the so-called operational delinquency, which excludes from the measurement debtors classified in situation 5, a category that includes loans with delinquencies over a year. This way, it provides a complementary reading on the behavior of the credit portfolio.
Javier Milei and Luis Caputo
According to the report from the Argentine Fintech Chamber, “situation 5 has a different weight in each portfolio.” In banks, it concentrates $1.5 trillion, while fintechs and other providers each register $0.9 trillion.
In parallel, financial entities have begun to implement refinancing plans aimed at facilitating the regularization of debts. Banco Nación and Banco Provincia already offer these alternatives, and Banco Ciudad announced a reduction in rates for those looking to catch up.
The evolution of early delinquency, which fell from 6.6% to 4.4% in the financial system, thus constitutes one of the main recent positive data regarding the behavior of loans with initial delinquencies.